 Services
 Technologies
 About
 Success


Generative AI in Banking: Real Use Cases from Vietnam’s Financial Sector
Share article


Table of Contents
Generative AI in banking means using models that produce language, summaries, and answers rather than models that only score or classify. A credit model tells you a number. A generative model reads fifty pages of a prospectus and writes the two-paragraph summary an analyst would have written by hand.
Vietnamese banks moved past the pilot stage during 2025 and 2026. TPBank now runs 20 production models across nine departments. VietinBank’s internal assistant answered 350,000 staff questions in its first two months. ACB Securities put a research assistant in front of its analysts and cut manual processing time by 60%.
What Is Generative AI in Banking?
Most banks already run something they call AI. The chatbot on the app, the credit scoring model, the alert when your card is used abroad. Those systems follow rules or predict a single value.
Generative AI works on language, so it handles the messy parts of banking that never fit neatly into a database field, such as annual reports, policy documents, call transcripts, and customer emails.
|
Traditional banking AI |
Generative AI |
|
| Input | Structured numbers and rules | Documents, chat, speech, mixed data |
| Output | A score, a flag, a yes or no | Written summaries, answers, drafts |
| Typical use | Credit scoring, fraud alerts | Research notes, assistants, explanations |
| Setup time | Months of model training | Weeks, using a foundation model |
| Main risk | Bias in the scoring | Confident answers that are wrong |
That last row is the question banks ask first, and it has a well-established answer. Production systems ground the model in the institution’s own verified documents and attach a traceable source to every reply. Add access controls, logging, and human review on anything a customer sees, and it becomes a control you manage like any other in the bank.
The institutions getting good results build those guardrails into version one, usually alongside a partner who has delivered the pattern before. The technology is ready for banking work, and that discipline is what separates a project that reaches production from one that stalls as a pilot.
How Widely Is Generative AI Used in Banking?
Adoption moved from experiment to budget line in about two years, and the published figures show how sharply:
- An EY-Parthenon survey in 2025 found 77% of banks had deployed or tested generative AI, up from 61% two years earlier, with close to 90% of financial institutions expecting fundamental change within two years
- Global bank spending on the technology is projected to climb from around $6 billion in 2024 to $85 billion by 2030, an increase of more than 1,400%
- Deloitte estimates leading investment banks could lift business performance by 27 to 35%, with revenue per employee rising by as much as $3.5 million
Numbers that large invite scepticism, so treat them as direction rather than destination. The useful signal is that spending has shifted from innovation labs into core operating budgets, which changes what a bank expects in return.
Which Banking Tasks Suit Generative AI
Some banking tasks suit this technology and others actively resist it. Being honest about the difference saves a lot of wasted budget.
|
Task |
Suitability |
Why |
| Summarising documents and reports | Strong | Language in, language out, with a human checking |
| Answering staff questions from internal policy | Strong | Errors are caught by people who know the answer |
| Drafting customer replies for agent review | Strong | Speeds up the work while keeping human judgement |
| Explaining a credit decision in plain language | Workable | Useful when the decision itself comes from a separate model |
| Making the credit decision | Poor | Regulators expect explainable, testable, auditable models |
| Producing exact financial calculations | Poor | Use a database or a calculation engine and let the model describe the result |
What Drives Adoption in Vietnamese Banks
Vietnam had 49 active commercial banks holding more than $565 billion in assets as of 2023, and adoption across them has been uneven. Research published in Financial Innovation surveyed 236 banking professionals in Vietnam and modelled which factors actually predict whether a bank adopts generative AI.
Organisational readiness came out strongest, meaning existing IT infrastructure and staff who already have the skills. Compatibility with current systems and competitive pressure followed close behind, with bank size and government support also registering. The finding matches what we see on projects.
Banks with a governed data platform already running move from idea to working assistant in weeks, and the rest spend their first months building foundations.
Competitive pressure explains the current pace. One bank launching a customer assistant puts the question on three other boardroom agendas within a quarter.
Six Use Cases Running in Vietnam Today
Vietnamese banks are pushing hard on this. Industry reporting from mid-2026 notes that nearly every bank in the market now runs some form of AI programme, with the leaders moving from isolated tools to shared platforms.
Investment Research Assistants
Bank: ACB Securities (ACBS).
Application: SMARTY, an investment analysis assistant built with our team at Renova Cloud on Amazon Bedrock.
Analysts had been spending hours pulling numbers out of FiinTrade, spreadsheets, and market reports before they could start thinking. SMARTY reads all three, drafts the company summary, and then answers follow-up questions in conversation, with each answer tied back to the document it came from. Two groups use it. Analysts use it to produce research faster and more consistently, and retail investors reach the same assistant inside the ACBS SMART trading app, which turns a research function that once served institutional clients into something an individual investor can query directly. Manual processing time dropped 60%.
Internal Staff Assistants
Bank: VietinBank.
Application: Genie, an assistant for employees rather than customers.
Genie is pointed at the bank’s own internal material, meaning product rules, operating procedures, and policy documents, so a branch employee can ask a question in Vietnamese and get the answer with a reference instead of calling head office or searching a shared drive. In its first two months it handled roughly 350,000 staff questions, with reported time savings on those queries reaching 95%. This category tends to be the safest starting point in any bank, since the audience is internal and every answer gets a human sanity check before it affects a customer.
Personalised Offers at Scale
Bank: Techcombank.
Application: A personalisation engine feeding the mobile app and outbound messaging.
The model is applied to transaction history and spending behaviour, and what comes out is a recommendation for a specific customer at a specific moment, such as a savings product for someone whose balance keeps building or a card offer matched to where they actually spend. The bank generated around 100 million personalised data points and sent more than 52 million financial suggestions to over 4 million customers. No human team writes 52 million messages, which is why this use case only exists in machine form. Techcombank has said its integrated technology platform is due in the third quarter of 2026, which would let the same personalisation run across its wider ecosystem.
Back-Office Automation
Bank: HDBank.
Application: Automation of repetitive internal processes.
The targets here are the tasks nobody enjoys, meaning document checking, data entry from scanned forms, and reconciliation between systems. A generative model can read a loan file, pull out the fields, and flag what looks inconsistent, which is work that previously needed a person reading line by line. HDBank reported cutting manual work by roughly 80%, which it valued at more than 92,000 working hours saved each year.
Customer Service in Vietnamese
Banks: Vietcombank, VPBank, and Techcombank.
Application: Customer-facing assistants in the mobile app and on the website.
Vietcombank’s VCB Chatbot handles routine enquiries, transaction requests, and product information around the clock. Older chatbots matched keywords, so a customer asking about a card fee in an unusual way got nothing useful. A generative assistant reads the intent instead, copes with regional wording and mixed Vietnamese and English, and hands the conversation to a human agent once the question moves into territory it should not decide, such as a dispute or an account change.
Fraud and Risk Explanations
Banks: Vietcombank and VietinBank.
Application: Risk and fraud systems, with a generative layer on top.
Vietcombank applies AI to credit risk analysis and to spotting unusual transactions, while VietinBank uses deep learning against card fraud. Those detection models output a score, and a score on its own tells an investigator very little. The generative layer writes the case summary, turning a flagged transaction into a readable explanation of which patterns triggered it and what the customer’s normal behaviour looks like. That shortens investigation time and leaves a written record a regulator can review later.
>>> Read more: Renova Cloud Becomes the First AWS Partner in Vietnam to Sign a Gen AI Collaboration Agreement
Case Study: The ACBS Investment Research Assistant on AWS
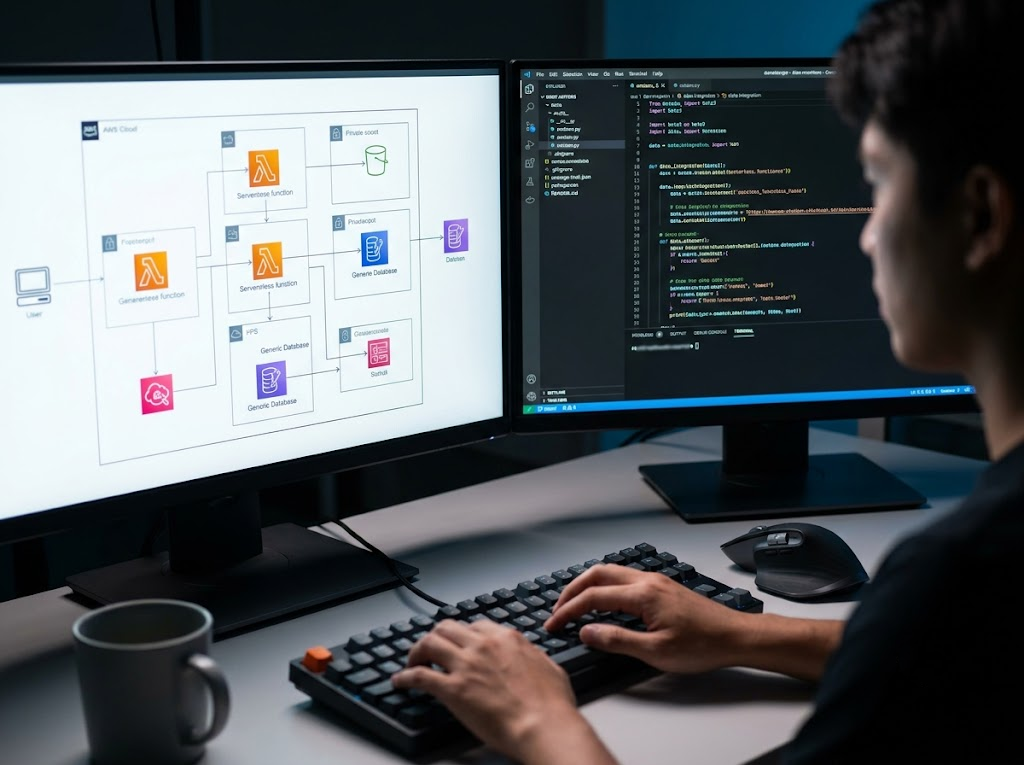
ACB Securities is one of Vietnam’s larger securities and investment firms, and it worked with Renova Cloud to build a generative AI investment analysis assistant on AWS. It is worth walking through in detail, because it shows what a production financial deployment involves beyond the model itself.
The Problem
ACBS analysts were assembling research by hand from disconnected sources, including FiinTrade, spreadsheets, and market reports. That produced three difficulties.
Reports took hours to compile, quality varied between analysts, and financial regulation demanded traceability that manual processes struggled to prove.
The Architecture
Our team built a serverless platform on AWS, which means there are no servers running when nobody is asking a question:
- Amazon Bedrock with with Claude 3 Sonnet and Knowledge Bases summarises the reports, documents, answers questions conversationally
- Amazon Redshift holds the structured market and company data
- Amazon OpenSearch Service indexes filings and research papers so answers stay grounded in real sources
- AWS Lambda and Step Functions coordinate the workflow across data sources in parallel
- Cognito, IAM, KMS, CloudTrail cover authentication, access control, encryption, and audit trail
Every AI answer is logged with its model version, data source, and prompt identifier. For a regulated firm this matters as much as accuracy, because an auditor can trace any output back to the material behind it.
The Results
|
Measure |
Outcome |
| Manual processing time | Down 60% |
| Automated report generation | Under 2.2 hours |
| Answer accuracy against verified sources | 92.4% |
| Query latency at peak load | Under 27 seconds |
| Cost control | Lighter models handle simple requests, reducing token spend |
>>> Read more: ACBS: Modernizing Investment Research and Advisory With Gen AI on AWS
The Rules Vietnamese Banks Must Design For
Vietnam moved quickly on regulation, and three instruments now shape any banking AI project. Compliance here is architecture work rather than paperwork, so bring it into the design phase.
The Law on Artificial Intelligence
Vietnam’s standalone AI Law took effect on 1 March 2026, placing the country among the earliest in Southeast Asia with nationwide rules. It uses a four-tier risk classification, puts oversight under the Ministry of Science and Technology, and gives systems already running before the effective date twelve months to align.
The SBV Draft Circular on AI in Banking
The State Bank of Vietnam has issued a draft circular covering AI use across the banking sector, applying to credit institutions, foreign bank branches, payment intermediaries, and credit information companies.
The draft requires risk classification and security testing before deployment, annual reviews of AI governance, clear disclosure to customers, and reporting of serious AI incidents to the SBV within 24 hours with a remediation report inside five working days. It also prohibits systems that produce bias or discrimination against vulnerable groups.
Decree 356 on Personal Data Protection
Decree 356/2025 replaced Decree 13/2023 from 1 January 2026 and singles out finance and banking for stricter treatment. Institutions must keep end-to-end processing logs, run annual compliance assessments, and disclose scoring and profiling activity in consent notices. Where AI processing affects an individual, the decree asks for transparency about the decision logic and an opt-out route.
>>> Read more: DevSecOps and Cloud Security
Work With Renova Cloud on Incorporating Generative AI in Banking
We are Renova Cloud, an AWS Premier Partner headquartered in Vietnam and a three-time AWS Partner of the Year for the country (2023, 2024, and 2026)
We were the first AWS partner in Vietnam to sign a generative AI Strategic Collaboration Agreement, and we built the ACBS investment analysis assistant now serving analysts and investors through the SMART app.
Our financial services work runs from data platforms and disaster recovery through to production generative AI, with the governance, encryption, and audit trails that Vietnamese banking regulation requires.
We handle use case selection, architecture, build, and the knowledge transfer that lets your team run the system afterwards.
Considering a generative AI project at your bank or securities firm? Talk to our team and we will walk through what is realistic for your data and your timeline.